US Bank Tests Proprietary Stablecoin for Cross-Border Payments on Stellar

Wellermen Image

US Bank Tests Proprietary Stablecoin Across Stellar Network

A US bank has tested its proprietary USBDC stablecoin in a cross-border transfer between its North American and European entities. The pilot ran on the public Stellar blockchain, offering a real-world test of whether bank-issued digital dollars can make international payments faster and more efficient.

The transaction matters because it moves stablecoins beyond crypto-native trading and into institutional settlement. By using Stellar’s public network, the bank is testing whether blockchain infrastructure can connect different regions without relying entirely on traditional correspondent banking channels.

USBDC was moved between the bank’s North American and European operations during the pilot. The snippet does not disclose the transaction size, timing, or the bank’s plans for a broader rollout, so the test should be viewed as an early proof of concept rather than a finished payments product.

What This Means for Crypto

In plain English, a proprietary stablecoin is a digital token issued by a bank and designed to maintain a stable value, typically against a national currency. If these tokens can move across borders securely, banks could settle transactions around the clock instead of waiting on slower legacy systems.

For traders and long-term investors, the test strengthens the case for stablecoins as core financial infrastructure. For builders, it highlights continued demand for public blockchains that can support compliant, high-volume payments without being limited to speculative crypto activity.

Market Impact and Next Moves

The immediate market reaction is likely mixed but strategically bullish for stablecoin and payments narratives. One pilot will not transform cross-border finance, yet institutional experiments can attract capital and encourage more banks to test blockchain-based settlement.

The main risks are regulation, liquidity, interoperability, and whether banks ultimately prefer private networks over public chains. The opportunity is clearer: if institutions expand these trials, networks such as Stellar could gain adoption from real payment flows rather than short-lived token speculation.

Stablecoin pilots are becoming more important than crypto hype cycles—but investors should wait for scale, repeat usage, and regulatory clarity before treating this test as a breakthrough.

Crypto Groups Sue to Block Illinois’ 0.2% Tax Before January Rollout

Wellermen Image

Crypto Groups Fight Illinois Tax Before January

Crypto Council for Innovation and the Blockchain Association are seeking to block Illinois’ proposed 0.2% crypto tax before it takes effect in January. The groups argue the levy is unconstitutional and could create expensive, complicated compliance demands for digital-asset businesses.

The challenge follows an earlier lawsuit targeting the Illinois tax, putting the state’s policy directly at odds with major crypto trade groups. Their argument centers on both legality and implementation: even a seemingly small tax could become costly when applied across frequent trades, transfers, and other digital-asset activity.

If the lawsuit succeeds, crypto companies and users in Illinois could avoid the new charge and the reporting burden tied to it. If the state prevails, exchanges, investors, and blockchain businesses may need to build new systems to track taxable activity before the January effective date.

What This Means for Crypto

The proposed 0.2% tax is not simply a fee on profits. Depending on how Illinois applies it, the levy could affect transaction activity and force businesses to collect, calculate, and report additional information. That is why industry groups warn that compliance costs could exceed the headline tax rate.

For traders, the dispute creates uncertainty over future transaction costs. Long-term investors may see limited immediate impact, but builders and crypto companies could reconsider operating in Illinois if the rules are viewed as too expensive or legally vulnerable.

Market Impact and Next Moves

The short-term market mood is likely mixed rather than broadly bullish or bearish. This is a state-level legal battle, not a direct threat to major tokens, but it adds to the regulatory uncertainty that already influences where crypto businesses choose to operate.

The key risk is that other states could adopt similar taxes if Illinois succeeds, raising costs across the industry. The opportunity for investors is less about trading the headline and more about watching the court fight for signals on whether U.S. crypto regulation is becoming clearer—or more fragmented.

Illinois’ crypto tax battle could determine whether digital-asset growth is taxed into compliance or pushed toward friendlier jurisdictions.

Strategy Market Cap Surges 80% in Three Months, Stock Jumps 54%

Strategy Says Market Value Increased by $31.6 Billion in Three Months

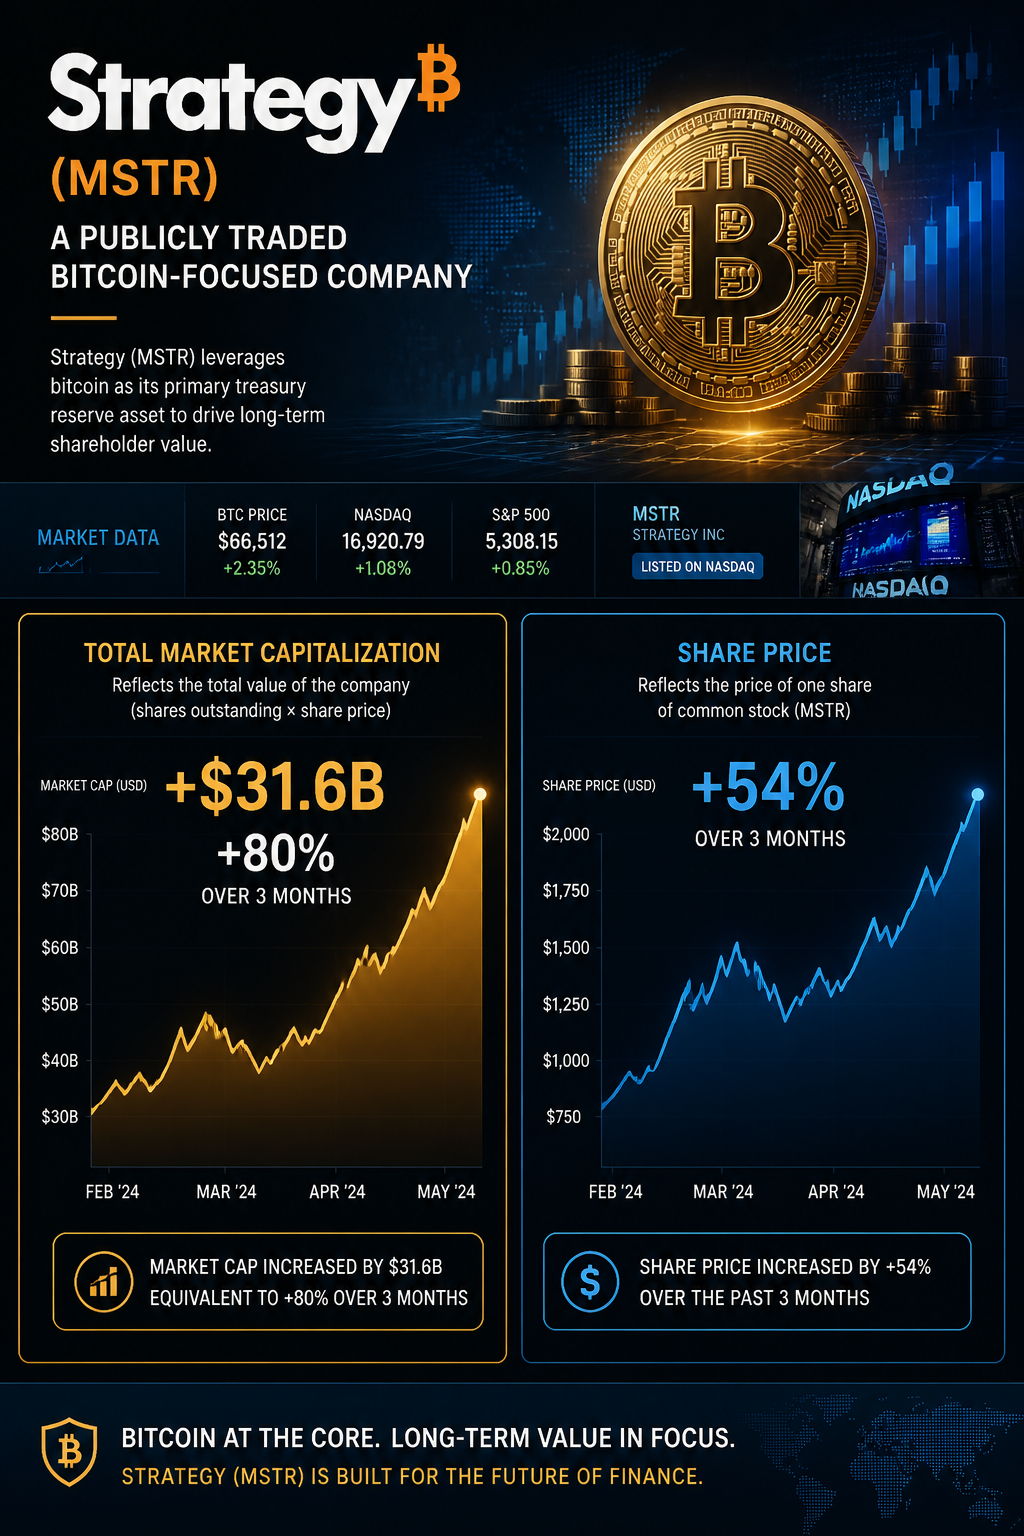
Strategy reported that its market capitalization rose by approximately $31.6 billion, or 80%, over the past three months, while the company’s Class A share price increased by about 54% during the same period.

Strategy Highlights Market Capitalization Growth

The company shared the figures in a post on X on Monday, accompanied by a chart summarizing the performance of its MSTR shares and overall market value.

“Last 3 months for MSTR: +$32B (+80%),” Strategy wrote in the post. The company’s figures indicate that its market capitalization grew at a faster rate than the price of its publicly traded Class A shares.

Market Capitalization and Share Price Measure Different Metrics

Market capitalization reflects the total value of a company’s outstanding shares, while the share price measures the value of an individual share. As a result, the two figures can move by different amounts when the number of shares outstanding changes.

Strategy’s Class A shares rose approximately 54% over the three-month period cited by the company. The market capitalization figure includes the broader value of the company’s outstanding equity.

Strategy’s Market Position

Strategy has become one of the most closely watched publicly traded companies in the cryptocurrency market because of its bitcoin-focused corporate treasury strategy. Its equity performance is often assessed alongside bitcoin prices and broader investor demand for publicly traded vehicles offering exposure to the asset.

LAPTOP Memecoin Turns Hunter Biden Controversy Into a High-Risk Crypto Bet

Wellermen Image

LAPTOP Memecoin Turns Political Controversy Into Speculation

A new memecoin called LAPTOP is using Hunter Biden’s laptop controversy as its core narrative, while openly admitting it has no utility. The project says founder tokens will remain locked for six months and that 2% of the supply is reserved for wallets that lost money on TRUMP, adding a political and retaliatory angle to an already volatile market.

The project appears designed to capitalize on the lingering attention around the laptop controversy and the broader rise of politically themed crypto tokens. Its disclosures are unusually direct: LAPTOP is not presenting a product, protocol, or long-term technical use case, but a tradable meme built around controversy and online momentum.

The token lock may offer some short-term reassurance by limiting immediate founder selling, but it does not remove the risk of a sharp collapse once attention fades or the lock expires. The 2% allocation for TRUMP-related losers is more symbolic than substantive, and investors should verify how eligibility, distribution, and wallet identification will actually work.

What This Means for Crypto

In plain English, LAPTOP is a narrative asset rather than an operating crypto project. Its value will depend heavily on social media attention, political headlines, trading liquidity, and speculation—not on revenue, technology, or network usage.

Traders may see an opportunity if the meme catches fire, but long-term investors face a much weaker foundation. Builders and serious market participants should view the launch as another example of how crypto can turn cultural and political moments into tradable assets almost instantly.

Market Impact and Next Moves

The immediate sentiment is likely mixed: politically themed memecoins can attract fast momentum, but the lack of utility also makes them vulnerable to rapid profit-taking and manipulation. A six-month founder lock reduces one obvious source of selling pressure, yet liquidity, contract controls, and ownership concentration remain critical risks.

The main opportunity is short-term exposure to a fresh narrative; the main danger is mistaking attention for adoption. Traders should avoid leverage, confirm the token’s contract and liquidity conditions, and remember that the unlock date could become a major exit-risk event.

LAPTOP may win the attention game, but without utility or durable demand, investors are ultimately betting on the controversy staying louder than the sell button.

Polymarket Ignored Warnings Before $10M Fraud Attack, Report Says

Polymarket Faces Scrutiny After Alleged $10 Million Debit-Card Fraud Scheme

Prediction-market platform Polymarket is facing scrutiny after bad actors allegedly used stolen debit cards to target its U.S. platform in a fraud scheme estimated at $10 million. The activity reportedly prompted payment processor Checkout.com to reject more than 80% of deposits as potentially fraudulent.

High Fraud-Rejection Rate Raises Compliance Concerns

The incident has fueled accusations that Polymarket prioritized user growth and expansion over safeguards designed to prevent payment fraud. The platform’s U.S. operations reportedly experienced a sharp increase in suspicious deposits linked to compromised debit cards.

Checkout.com, which processes payments for the platform, responded by blocking a significant majority of deposits after identifying patterns associated with fraudulent transactions. The scale of the rejections highlights the challenges facing online prediction markets as they expand their customer bases and payment infrastructure.

Questions Over Risk Controls

The episode has also raised questions about whether Polymarket acted quickly enough on warnings related to suspicious payment activity. Effective controls typically include identity verification, transaction monitoring and measures to detect stolen-card use before funds are accepted.

Fraud involving payment cards can expose platforms to financial losses, chargebacks and increased scrutiny from payment providers. It can also affect legitimate users if processors respond by imposing stricter deposit restrictions.

Broader Implications for Prediction Markets

Prediction markets allow users to trade contracts tied to the outcomes of events, including elections, economic developments and other real-world activities. As these platforms attract more users, their ability to manage fraud, comply with financial regulations and maintain reliable payment systems is becoming increasingly important.

The reported incident underscores the operational risks associated with rapid expansion. Payment processors may impose tighter controls or reject more transactions when fraud rates rise, potentially limiting a platform’s ability to onboard users and process deposits.

DraftKings Shelved Problem-Gambling AI While Targeting High-Risk Bettors

New York Times Reports DraftKings Targeted Gamblers Predicted to Lose the Most

DraftKings developed a machine-learning model to direct promotional offers toward customers it predicted would lose the most money, while internal efforts to identify potential problem gamblers were discontinued, according to a New York Times investigation published Saturday.

Model Focused on Expected Losses

The Times said its reporting was based on interviews with current and former employees familiar with the company’s practices. The investigation described an internal system designed to identify gamblers considered especially valuable because of their projected losses.

The reported strategy raises questions about how online gambling companies use customer data and predictive analytics to personalize promotions. Such systems can analyze betting behavior, spending patterns and engagement to determine which customers receive targeted offers.

Problem-Gambling Detection Efforts Shelved

According to the report, DraftKings also pursued technology intended to predict which customers might develop gambling problems. Those efforts were later shelved, the newspaper reported.

The contrast between attempts to identify likely high-loss customers and the decision to discontinue problem-gambling prediction initiatives has drawn scrutiny from gambling researchers and consumer-protection advocates.

DraftKings Disputes the Characterization

DraftKings rejected the Times’ characterization of its practices. The company has not publicly confirmed the specific details of the reported model or explained why the internal problem-gambling initiative was discontinued.

The report adds to ongoing concerns about the use of artificial intelligence and machine learning in online betting, particularly as operators expand personalized marketing and risk-monitoring systems.

Dogecoin Jumps 15% as Bitcoin Holds Above $85,000 in Market Rebound

Short Squeeze Loses Momentum After $844 Million in Liquidations

A wave of forced buying that resulted in approximately $844 million in losses for cryptocurrency short sellers has subsided, leaving Bitcoin largely unchanged over the past hour. Zcash (ZEC) was the only major token trading lower during the period.

Short Sellers Absorb Heavy Losses

The forced buying was driven by the liquidation of leveraged short positions. When these positions are closed, exchanges typically buy the underlying assets, adding upward pressure to the market and potentially accelerating price moves.

Bitcoin Holds Steady as ZEC Declines

After the liquidation-driven move, Bitcoin remained broadly flat on a one-hour basis. Among major cryptocurrencies, Zcash was the only token reported to be in negative territory, suggesting that broader market momentum had eased following the short-covering activity.

ECB to Invest Directly in Tokenized Securities Through Pontes

ECB Prepares to Invest in Tokenized Euro-Denominated Securities

The European Central Bank has begun preparations to invest a small portion of its own-funds portfolio in tokenized euro-denominated securities, marking a potential shift from developing tokenized-settlement infrastructure to using it directly.

Initial Investment Focus

The planned investments are separate from the ECB’s monetary-policy operations. They would be made through the central bank’s own-funds portfolio, a non-monetary-policy pool.

The initial eligible assets are expected to include securities issued by:

  • Euro-area central governments;
  • Regional governments and agencies; and
  • European supranational institutions.

Tokenized securities are digital representations of financial assets recorded and transferred using distributed-ledger or similar technology.

Settlement Planned Through Pontes

The ECB intends for the purchases to settle in central-bank money through Pontes, the Eurosystem’s infrastructure for settling tokenized financial assets.

The plan would make the ECB not only a provider of tokenized-settlement infrastructure for market participants but also a potential user of that infrastructure for its own portfolio transactions.

No Purchases Have Been Completed

The ECB’s announcement concerns preparatory work. It has not stated that any tokenized securities have already been purchased for the own-funds portfolio.

Operational timing and execution details will be determined after the preparation phase and a subsequent review by the ECB’s Executive Board.

If implemented, the initiative could move tokenization beyond pilot programs and into the routine management of an institutional investment portfolio. For now, however, the development represents a planned use case for Pontes rather than completed trades.

Kalshi Wins Again as Court Slams CFTC Overreach on Election Contracts

Wellermen Image KALSHI WINS AGAIN AS COURT SLAMS CFTC’S OVERREACH
A federal appeals court has refused to block KalshiEX from offering election contracts, effectively slapping the CFTC for trying to stretch its power beyond what Congress granted. The decision keeps the trading venue open for now and signals that federal regulators cannot simply declare something off-limits without clear statutory authority.

The fight started when Kalshi sought CFTC approval to list contracts tied to U.S. election outcomes. The agency said no, arguing that letting people bet on elections would be “contrary to the public interest.” Kalshi sued, claiming the CFTC lacked the legal power to block contracts based solely on its own view of morality or politics. A district judge agreed and ordered the agency to let the contracts trade; the CFTC immediately asked the D.C. Circuit to freeze that order while it appealed. On October 2, the appeals court denied the stay, letting the lower-court ruling stand for now.

Judges on the three-member panel focused on whether the CFTC had shown a likelihood of success on the merits and whether halting trading would cause irreparable harm. They found the agency’s public-interest argument too vague to override the Commodities Exchange Act’s presumption that exchanges can list contracts unless they violate specific statutory bans. The court also noted that Kalshi had already invested heavily in compliance systems, so the balance of equities tilted toward letting trading begin. In short, the CFTC lost this round and must now either prove its case on a full appeal or watch the contracts go live.

The ruling narrows the CFTC’s discretion to veto products on broad policy grounds. The agency still regulates fraud and manipulation, but it cannot simply brand an instrument “bad for society” and shut it down without pointing to concrete statutory language.

For crypto traders and DeFi builders, the decision is a green light: prediction markets, event contracts, and other novel instruments now face a lower regulatory hurdle. Expect more election-related tokens, on-chain betting protocols, and exchange listings that sidestep traditional gatekeepers. Stablecoin issuers and decentralized platforms that offer similar exposure should still watch for fraud rules, but the threat of a blanket CFTC veto just shrank.

Regulators will keep testing their reach, yet today’s order shows that judges can—and will—push back when agencies stretch beyond the text of the law.

Court Denies Envy Blockchain’s Last-Ditch Bid to Skip Trial

Wellermen Image COURT KILLS BLOCKCHAIN COMPANY’S LAST-DITCH BID TO SKIP TRIAL
Envy Blockchain, NV Landco 1, and CEO Stephen DeCani just lost their emergency bid to halt a Texas district-court case mid-stream. The El Paso Court of Appeals refused to issue a writ of mandamus that would have frozen discovery, sanctions motions, and a looming trial date, effectively telling the company that litigation pain cannot be sidestepped by appellate shortcut. The ruling lands at a moment when crypto firms already feel the squeeze of both civil suits and regulatory scrutiny.

The fight began when a Texas investor accused the three parties of misusing funds raised for a planned Bitcoin-mining facility. After the district judge allowed broad discovery and sanctioned the defendants for discovery abuse, Envy and its co-defendants raced to the appellate court, arguing the lower court had no jurisdiction because the mining project never left the idea stage and the claims sounded in securities fraud—an area they claimed was preempted by federal law. The panel cut through the argument in a single paragraph: mandamus is an extraordinary remedy, and Envy had failed to show the district court was “clearly and indisputably” out of bounds.

In plain terms, Texas courts will keep jurisdiction, evidence will be exchanged, and the case heads toward either settlement or a jury verdict. That means more documents, more depositions, and more potential headlines about missing investor money. For crypto projects still structured as Texas LLCs or still courting Lone-Star capital, the decision is a reminder that state-court dockets move faster than federal crypto rule-making.

From a market perspective, the ruling quietly tilts power toward plaintiffs and state attorneys general while the SEC and CFTC continue to spar over digital-asset turf. Every new document unsealed in discovery could feed enforcement theories on unregistered securities or commodities, raising due-diligence costs for exchanges listing tokens tied to mining ventures. Traders pricing governance tokens or mining-related equities will now bake in a higher Texas-litigation premium.

Bottom line: if your tokenomics live in Texas courts, plan for discovery, not just disclosure.

Privilege Wins as Seventh Circuit Blocks CFTC’s Fast-Track for Internal Memos in Wheat-Futures Case

Wellermen Image COURT TELLS CFTC: HANDS OFF INTERNAL DOCUMENTS
The Seventh Circuit just blocked the CFTC’s attempt to force Kraft and Mondelēz to hand over privileged materials in a wheat-futures manipulation probe. By denying the agency’s petition for a writ of mandamus, the court told regulators they cannot shortcut normal discovery rules—even when the stakes involve futures markets. That single procedural ruling could slow CFTC enforcement and give exchanges and traders breathing room.

The dispute began when the agency accused the two food giants of rigging the wheat market. Rather than wait for ordinary document requests, the CFTC asked the district court to compel production of internal memos that the companies claimed were protected by attorney-client privilege. The district judge refused, and the agency ran straight to the appeals court for an extraordinary writ—an order that would have forced disclosure immediately. Three Seventh Circuit judges heard the petition and, in a short opinion, said the CFTC had not shown the “clear and indisputable” right needed for mandamus.

What the judges actually ruled is simple: privilege fights belong in the trial court first, and regulators get no special fast-pass. Kraft and Mondelēz keep their documents under seal for now. The CFTC can still fight the privilege claims line-by-line, but it cannot leapfrog the process. The companies win a tactical victory; the agency loses momentum and precedent that would have made future fishing expeditions easier.

In plain English, the court reminded the CFTC that administrative muscle does not erase centuries-old protections for lawyer-client communications. The ruling narrows the agency’s toolkit at the very moment it is expanding oversight into crypto-linked commodity products. If the same logic applies to digital-asset subpoenas, exchanges and DeFi protocols gain a new shield against broad document grabs.

For crypto markets, the decision tilts the balance toward due process over speed. Traders and platforms now have slightly stronger grounds to push back when the CFTC—or the SEC citing similar theories—demands privileged strategy memos. That does not stop enforcement, but it raises the cost and calendar time of every case. Decentralized projects that never kept traditional legal memos may dodge the issue altogether, while listed exchanges face higher compliance spend.

The takeaway: regulators just learned they cannot treat privilege as an after-thought; expect slower, more expensive enforcement—and a short-term lift in risk appetite among exchanges and traders who were bracing for wide-ranging document sweeps.

BitMine’s ETH Treasury Nears 6 Million Tokens, Reaching $17.1B

BitMine Reports Nearly 6 Million ETH in Treasury Holdings

BitMine Immersion Technologies reported 5,983,940 ETH in its treasury, putting the company just below the 6 million-token mark. The company said its combined holdings, including cryptocurrency, cash, securities and strategic investments, were valued at $17.1 billion.

Ethereum Holdings Approach 6 Million Tokens

In a filing dated September 21, BitMine disclosed that it held 5,983,940 ETH. The company said the position represented approximately 4.9% of the circulating Ethereum supply figure cited in the filing.

The disclosure does not indicate that BitMine has crossed the 6 million ETH threshold. It also does not provide details about future purchases or specify when the company might reach that level.

Broader Treasury Portfolio

Beyond its Ethereum holdings, BitMine reported 212 BTC and $714 million in cash and marketable securities. The company also disclosed a $180 million stake in Beast Industries and a $105 million stake in Eightco.

Combined, the disclosed assets were valued at $17.1 billion. While ETH represents the dominant component of BitMine’s treasury, the filing shows that the company maintains a broader portfolio of digital assets, liquid investments and strategic equity positions.

Growing Role of Ethereum Treasury Companies

Corporate cryptocurrency treasury strategies have historically focused primarily on Bitcoin. BitMine’s holdings highlight the expansion of the model into Ethereum, giving the company exposure to ETH’s market price as well as developments involving staking, network activity and institutional demand for Ethereum-based assets.

The scale of BitMine’s position means changes to its treasury could attract increased attention from the broader Ethereum market. For now, the filing confirms that BitMine holds 5,983,940 ETH and values its total disclosed treasury assets at $17.1 billion.

Old Court Order, Fresh Crypto Scrutiny: SEC Keeps Bilzerian Injunction Alive

Wellermen Image Court Reopens 1989 Bilzerian Case, Warns Crypto Mimics
SEC wins round in 34-year-old Bilzerian saga, signals fresh appetite for old grudges and new targets. The ruling keeps decades-old injunctions alive and warns anyone using complex structures to dodge disclosure rules that time is no shield.

The fight started in 1989 when the SEC accused Bilzerian of secretly amassing stock in several public companies through undisclosed offshore entities and false filings. After a 1993 civil judgment and 2001 injunction barring him from “commencing or causing the commencement of any legal proceeding” without first giving the SEC notice, Bilzerian’s estate and related parties asked the court to end the restrictions, arguing the passage of time and changed circumstances made them obsolete. Judge Royce Lamberth refused. The court held that the original injunction remains necessary because the defendants never demonstrated full compliance or an end to the risk of future violations. The SEC keeps its enforcement tool; defendants stay tethered to prior restraints.

In plain terms, the judge said an old order is still an order. Once a court bars someone from using legal maneuvers to hide ownership or evade disclosure, that bar does not expire simply because years pass. The ruling keeps the 2001 language intact, meaning any future attempt to litigate without SEC notice can trigger contempt findings and fresh penalties.

The decision widens the SEC’s practical reach. While the case itself is not about crypto, the precedent matters because many token projects today rely on layered entities, offshore vehicles, and ambiguous disclosures—the same toolkit Bilzerian used. Exchanges and DeFi protocols that structure tokens to skirt securities classification face the reminder that regulators can dust off decades-old injunctions if similar patterns appear. Stablecoin issuers and liquidity providers who obscure beneficial ownership should expect heightened scrutiny; traders betting on regulatory gray zones just saw one shrink.

Old grudges do not die; they just wait for the next cycle.

Appeals Court Narrows SEC’s Crypto Securities Power, Shifts Control to CFTC

Wellermen Image **SEC Suffers Major Blow as Court Narrows Crypto Oversight Powers**
A federal appeals court just handed the crypto industry a significant legal victory, sharply limiting the SEC’s ability to treat most digital assets as securities. The ruling could reshape how tokens are classified, how exchanges operate, and how the SEC pursues enforcement cases going forward.

The case began when the SEC sued a major crypto exchange for allegedly selling unregistered securities. The agency argued that nearly all tokens on the platform met the Howey test because buyers expected profits from the issuer’s efforts. The exchange fought back, claiming the tokens were commodities or utility assets with no profit-sharing contract. After months of litigation, the appeals court agreed the SEC had overreached, ruling that most tokens do not automatically qualify as securities simply because they are listed on a trading platform.

The judges found that the SEC failed to prove buyers were investing money in a common enterprise with the expectation of profits derived solely from the efforts of others. Instead, the court emphasized that many tokens function more like commodities or consumer goods, especially when their value is driven by market forces rather than any single promoter. The decision also criticized the SEC for failing to provide clear guidance, calling its enforcement approach “arbitrary and inconsistent.”

This ruling significantly weakens the SEC’s position in ongoing and future crypto cases. It signals that courts may require more specific evidence of investment contracts rather than blanket classifications. The decision could force the agency to rethink its enforcement strategy and may embolden exchanges and DeFi projects to resist broad regulatory demands.

The ruling shifts power toward the CFTC for commodity-like tokens and reduces legal uncertainty for exchanges that list non-security assets. It also puts pressure on lawmakers to create clearer rules, as courts are now less willing to let the SEC define the entire market through enforcement alone. Stablecoin issuers and DeFi protocols may face lower legal risk, while the SEC will likely face higher hurdles in proving violations.

For traders and platforms, the message is clear: regulatory risk has not vanished, but the balance has tilted. This decision opens the door for innovation while reminding everyone that the fight over who controls crypto’s future is far from over.

Offshore Crypto Funds Escape CFTC Jurisdiction, Court Rules

Wellermen Image CFTC Stung as Appeals Court Snaps Leash on Its Power

Judges just told the CFTC it can’t stretch its reach across oceans to punish traders who never set foot in the U.S., a ruling that immediately weakens the agency’s long-running claim to global authority over crypto and derivatives markets. The Seventh Circuit’s decision hands the Conway Family Trust a win and sends a clear message that geography still matters in regulation.

The trust had parked money with a Cayman Islands fund that later blew up. When the CFTC tried to fine the trust for failing to register as a commodity pool operator, the trustees fought back, arguing the trades happened offshore and the CFTC had no jurisdiction. The agency countered that the fund used U.S. clearing firms, giving it a hook. The panel rejected that theory, holding that merely routing orders through American infrastructure does not turn a foreign pool into a domestic one.

The court zeroed in on the statute’s language: registration rules apply only to pools “operated” inside the United States. Because the trust’s decisions were made in the Caymans, and the CFTC offered no evidence that the trust itself controlled U.S.-based trading, the agency lacked authority. The ruling slams the door on the CFTC’s attempt to bootstrap jurisdiction from downstream clearing activity.

In plain terms, the decision blocks the CFTC from hauling offshore crypto funds and DeFi protocols into U.S. court just because they clear trades on American exchanges or touch U.S. liquidity. Offshore entities now have a stronger shield against registration demands, and U.S. platforms that serve them face less pressure to police foreign counterparties.

Traders and exchanges gain breathing room to structure offshore vehicles without automatic U.S. oversight, but stablecoins and tokens that clear significant volume through domestic rails remain exposed if any U.S. entity exercises actual control. Expect more Cayman and Singapore vehicles, tighter structuring around order routing, and a cautious uptick in offshore DeFi activity until regulators find a new hook.

The message is blunt: location still shapes liability, and the CFTC’s extraterritorial reach just got shorter.

×